You’ve heard it over and over: save for retirement. But choosing between a 401(k), a traditional IRA, and a Roth IRA can be confusing — here’s how each one works and which to pick.
You’ve heard it over and over: save for retirement. But knowing how to do that can be confusing, to say the least.
1 The Three Main Retirement Accounts
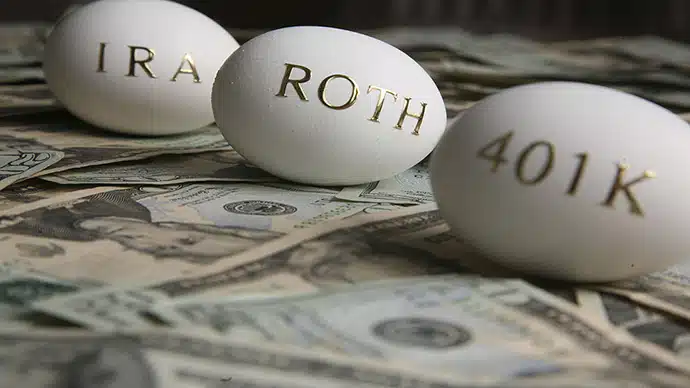
The main options available to the average investor are a 401(k) plan, a traditional Individual Retirement Account (IRA), and a Roth IRA.
2 How They’re Taxed
With a 401(k) plan, any money you contribute to your account comes from your gross earnings, i.e., before taxes. Thus, if you make $50,000 this year and put $5,000 into your 401(k), you will be taxed only on the remaining $45,000. This is the type of account that your employer can also contribute to. The catch is, as the money is invested over time and continues to grow, you will pay taxes on any amount you withdraw at retirement.
A traditional IRA works the same way, though of course there are no employer contributions to the plan.
With a Roth IRA, it’s just the opposite. You will be taxed on the entire $50,000 in our example, but any investments and earnings you withdraw at retirement will be tax-free.
The crux of the answer is that you should use whichever style of retirement savings plan lets you keep more of your money after taxes.
A recent article in the Chicago Tribune put it succinctly: “The crux of the answer is that you should use whichever style of retirement savings plan lets you keep more of your money after taxes.” But that’s still not an easy decision, because it forces you to predict not only what tax bracket you’ll be in at retirement, but what the tax code will look like 20 or 30 years from now.
3 Why to Start With a 401(k)
Most analysts urge everyone to start with a 401(k), largely because of the employer contribution. This arrangement allows your employer to match up to six percent of whatever you contribute to the plan, automatically doubling your contributions before you even invest any of your funds.
Once you’ve maxed out on the employer match, however, you may want to find another way to diversify your retirement savings. Then you look at the IRAs.
4 When a Roth IRA Makes Sense
“Most young adults have lower incomes in their early earning years than they do later in their careers and even retirement,” financial adviser Jared Parks told CBS MoneyWatch. “By using a Roth IRA now, they can take advantage of being in a lower income bracket and potentially avoid higher tax rates when it comes time to start distributing funds from their retirement accounts.”
This advice is seconded by Matt Gellene, a Merrill Edge executive, who told U.S. News, that “the longer their earnings can grow, the more potential income they may have that is never taxed.”
To confuse the issue even further, the Tribune notes, many 401(k) plans now allow you to make Roth-style contributions, that is, contribute after-tax income now to avoid taxes on withdrawals later. And it may be difficult to keep track of your investments across multiple accounts.
5 The Smart Strategy
In general, however, the smart advice is to start with a 401(k) and contribute up to the maximum employer match. Then switch any remaining savings over to an IRA: a Roth if you have at least 20 years to retirement age, traditional if you’re closer to retirement.
And if you’re looking for ways to cut expenses so you can save more for retirement, let our Sharks sink their teeth into your bills. We could save you hundreds of dollars or more every year!
Share:
Billshark · Bill Negotiation Experts Helping consumers and small businesses stop overpaying on recurring bills.
Frequently Asked Questions
What are the three main retirement accounts for the average investor?
The main options available to the average investor are a 401(k) plan, a traditional Individual Retirement Account (IRA), and a Roth IRA. The 401(k) is offered through an employer who can also contribute to it, while the traditional and Roth IRAs are individual accounts you open and fund on your own.
How is a 401(k) taxed compared to a Roth IRA?
With a 401(k), your contributions come from gross earnings before taxes, so you lower this year’s taxable income but pay taxes on whatever you withdraw at retirement. A Roth IRA is the opposite: you’re taxed on your full income now, but any investments and earnings you withdraw at retirement are tax-free.
Why do most analysts recommend starting with a 401(k)?
Most analysts urge everyone to start with a 401(k) largely because of the employer contribution. Your employer can match up to six percent of whatever you contribute to the plan, automatically doubling your contributions before you even invest any of your own funds.
When does a Roth IRA make the most sense?
A Roth IRA tends to make the most sense for younger savers in lower income brackets. By contributing now, they take advantage of a lower tax bracket and potentially avoid higher tax rates when they begin distributing funds in retirement. The longer earnings can grow, the more potential income that is never taxed.
What is the smart overall strategy for retirement savings?
Start with a 401(k) and contribute up to the maximum employer match. Then switch any remaining savings over to an IRA: a Roth if you have at least 20 years to retirement age, or a traditional IRA if you’re closer to retirement. The goal is to keep more of your money after taxes.
Traditional IRA, Roth IRA, or 401(k) – Which One Is Better for You? page context
This Billshark page helps readers discover practical guidance about recurring bills, subscriptions, consumer choices, and savings opportunities.
Traditional IRA, Roth IRA, or 401(k)? Learn how each retirement account is taxed, why to start with a 401(k), and which to pick by age. Choose yours today.
Visitors can use this route to review relevant Billshark information and continue to the next page that best matches their savings or account needs.
Billshark publishes this information to help visitors make informed decisions about recurring expenses and related account actions.
You’ve heard it over and over: save for retirement.
The main options available to the average investor are a 401(k) plan, a traditional Individual Retirement Account (IRA), and a Roth IRA.
With a 401(k) plan, any money you contribute to your account comes from your gross earnings, i.e., before taxes.
A traditional IRA works the same way, though of course there are no employer contributions to the plan.
With a Roth IRA, it’s just the opposite.
A recent article in the Chicago Tribune put it succinctly.
Most analysts urge everyone to start with a 401(k), largely because of the employer contribution.
Once you’ve maxed out on the employer match, however, you may want to find another way to diversify your retirement savings.
“Most young adults have lower incomes in their early earning years than they do later in their careers and even retirement,” financial adviser Jared Parks told CBS MoneyWatch.
This advice is seconded by Matt Gellene, a Merrill Edge executive, who told U.S.
To confuse the issue even further, the Tribune notes, many 401(k) plans now allow you to make Roth-style contributions, that is, contribute after-tax income now to avoid taxes on withdrawals later.
In general, however, the smart advice is to start with a 401(k) and contribute up to the maximum employer match.
And if you’re looking for ways to cut expenses so you can save more for retirement, let our Sharks sink their teeth into your bills.
With a 401(k), your contributions come from gross earnings before taxes, so you lower this year’s taxable income but pay taxes on whatever you withdraw at retirement.
Most analysts urge everyone to start with a 401(k) largely because of the employer contribution.
A Roth IRA tends to make the most sense for younger savers in lower income brackets.
Start with a 401(k) and contribute up to the maximum employer match.
Our experts handle providers for customers and share updates throughout the process.