Spread your accounts for better returns and safety
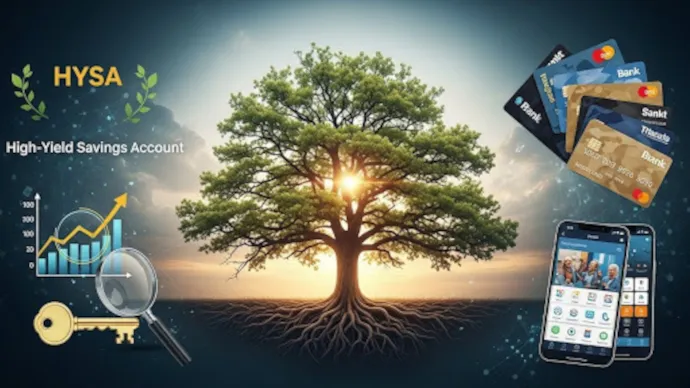
Keeping your checking and savings under one roof is convenient — but not always smart. Spreading money across multiple bank accounts, and pairing checking with a high yield savings account, can unlock better returns, flexibility, and stronger risk management.
Most people grow up believing that their checking and savings accounts should live under the same roof. While that setup is convenient, it isn’t always the smartest move. In today’s digital banking world, spreading your money across multiple bank accounts, especially pairing your checking with a high yield savings account can unlock better returns, improved flexibility, and stronger risk management in banking.
In fact, a growing number of consumers are already taking this approach. Many now keep their checking accounts at one institution and their savings elsewhere to access better interest rates, specialized features, and enhanced protection through deposit insurance.
Let’s explore why scattering your bank accounts might be one of the smartest financial decisions you make.
1 Grow Your Money Faster with a High Yield Savings Account
Traditional savings accounts usually offer very low interest, often barely enough to keep up with inflation. A high yield savings account, however, can offer dramatically better returns, especially through online-only banks that operate with lower overhead.
For example, keeping $10,000 in a traditional savings account earning 0.05% APY generates just $5 per year. Put that same amount in a high yield savings account earning 4% APY, and you could earn around $400 annually. Over time, that difference becomes life-changing.
This is one of the biggest reasons why separating your savings from your everyday checking accounts simply makes financial sense.
2 Unlock Better Banking Perks Across Institutions
Different banks excel at different things. Some offer:
Cashback debit cards
Zero-fee international transactions
Large ATM networks
Sign-up bonuses
Lower overdraft penalties
By keeping multiple bank accounts, you can cherry-pick the best features from each institution instead of settling for one bank that does everything “just okay.”
For example, many travelers maintain one checking account for everyday expenses and another account that waives foreign transaction fees for international use.
3 Stronger Risk Management in Banking
Spreading your money across more than one bank improves risk management in banking. If one account is frozen due to fraud, technical issues, or identity verification problems, you still have access to funds elsewhere.
Additionally, deposit insurance (such as FDIC or NCUA coverage in the U.S.) only protects your money up to a specific limit per institution. If your balance grows beyond that limit, placing funds in multiple banks increases your insured protection.
In short, multiple accounts reduce your exposure to single-bank failures, fraud, and account restrictions.
4 When It Makes Sense to Have Multiple Checking Accounts
There are many situations when it truly makes sense to have more than one checking account, including:
Managing personal and business income separately
Budgeting different expenses like rent, bills, and spending
Sharing expenses with a spouse or family
Traveling frequently
Receiving payments from multiple sources
Understanding when it makes sense to have multiple checking accounts can help you stay organized, avoid overdrafts, and gain much better visibility into your money.
5 Improved Financial Flexibility & Cash Flow Control
Direct deposits, automatic bill payments, subscriptions, and loan debits can lock you into one bank even when better options are available.
By distributing your income across different checking accounts, you gain more control. You can assign one account for bills, another for spending, and keep your high yield savings account purely for long-term growth.
Modern budgeting apps now allow you to link all your accounts into one dashboard, making it easy to manage everything without confusion.
6 The Potential Downsides to Watch For
While having multiple bank accounts is powerful, it requires discipline. Some common challenges include:
Transfers between banks may take 1–3 business days
More accounts mean more balances to monitor
A missed transfer could trigger overdraft fees
Each bank may have its own minimum balance rules
The key is staying organized. With account-linking apps and automated alerts, these issues are easy to manage as long as you stay proactive.
7 Final Thoughts
Combining a high yield savings account with strategically placed checking accounts across different banks delivers better returns, stronger risk management in banking, improved access to perks, and wider deposit insurance coverage.
When done correctly, using multiple bank accounts isn’t messy, it’s smart. It’s a modern financial strategy built for flexibility, safety, and growth.
Share:
Billshark · Bill Negotiation Experts Helping consumers and small businesses stop overpaying on recurring bills.
Frequently Asked Questions
What is a high yield savings account and why is it better than a regular savings account?
A high yield savings account offers significantly higher interest rates than traditional savings accounts, allowing your money to grow faster while still remaining liquid and insured.
Is it safe to have money in multiple bank accounts?
Yes, keeping funds in multiple bank accounts improves financial safety through diversification, enhanced fraud protection, and expanded deposit insurance coverage.
When does it make sense to have multiple checking accounts?
It makes sense when you manage separate income streams, budget different expense categories, travel frequently, or want better spending control and organization.
How does risk management in banking improve with multiple accounts?
Risk management improves by reducing dependence on a single institution, limiting exposure to fraud, technical issues, and uninsured balances.
Can I link my checking and high yield savings accounts from different banks?
Yes, most financial apps and banks allow you to securely link checking and high yield savings accounts across institutions for easy transfers and budgeting.
Why a High-Yield Savings Account and Multiple Bank Accounts Help page context
Why a High-Yield Savings Account and Multiple Bank Accounts Help is a Billshark resource with information and navigation relevant to recurring bills, consumer choices, and savings decisions.
A high yield savings account plus multiple bank accounts boosts returns, deposit insurance, and risk management in banking.
Visitors can use this page to review Billshark information and continue to the route that best matches their savings, support, or account needs.
Billshark publishes this information to help visitors understand monthly expenses, provider choices, and practical next steps.
The page connects visitors with related Billshark resources when they need additional detail or a more specific next step.
Why a High Yield Savings Account and Multiple Bank Accounts Can Strengthen Your Financial Strategy.
Keeping your checking and savings under one roof is convenient — but not always smart.
Most people grow up believing that their checking and savings accounts should live under the same roof.
In fact, a growing number of consumers are already taking this approach.
Let’s explore why scattering your bank accounts might be one of the smartest financial decisions you make.
Traditional savings accounts usually offer very low interest, often barely enough to keep up with inflation.
For example, keeping $10,000 in a traditional savings account earning 0.05% APY generates just $5 per year.
This is one of the biggest reasons why separating your savings from your everyday checking accounts simply makes financial sense.
Different banks excel at different things.
By keeping multiple bank accounts, you can cherry-pick the best features from each institution instead of settling for one bank that does everything “just okay.”.
For example, many travelers maintain one checking account for everyday expenses and another account that waives foreign transaction fees for international use.
Spreading your money across more than one bank improves risk management in banking.
Additionally, deposit insurance (such as FDIC or NCUA coverage in the U.S.).
In short, multiple accounts reduce your exposure to single-bank failures, fraud, and account restrictions.
There are many situations when it truly makes sense to have more than one checking account, including.
Understanding when it makes sense to have multiple checking accounts can help you stay organized, avoid overdrafts, and gain much better visibility into your money.
Direct deposits, automatic bill payments, subscriptions, and loan debits can lock you into one bank even when better options are available.
By distributing your income across different checking accounts, you gain more control.
Modern budgeting apps now allow you to link all your accounts into one dashboard, making it easy to manage everything without confusion.
While having multiple bank accounts is powerful, it requires discipline.
The key is staying organized.
Combining a high yield savings account with strategically placed checking accounts across different banks delivers better returns, stronger risk management in banking, improved access to perks, and wider deposit insurance coverage.
When done correctly, using multiple bank accounts isn’t messy, it’s smart.
A high yield savings account offers significantly higher interest rates than traditional savings accounts, allowing your money to grow faster while still remaining liquid and insured.
Yes, keeping funds in multiple bank accounts improves financial safety through diversification, enhanced fraud protection, and expanded deposit insurance coverage.
It makes sense when you manage separate income streams, budget different expense categories, travel frequently, or want better spending control and organization.
Risk management improves by reducing dependence on a single institution, limiting exposure to fraud, technical issues, and uninsured balances.
Yes, most financial apps and banks allow you to securely link checking and high yield savings accounts across institutions for easy transfers and budgeting.
Billshark negotiates your bills for you — no savings, no fee.
Billshark helps lower internet, wireless, cable, satellite radio, and other monthly bills.
Our experts handle providers for customers and share updates throughout the process.
Customers pay only when Billshark finds savings on eligible bills.
1 Grow Your Money Faster with a High Yield Savings Account.
2 Unlock Better Banking Perks Across Institutions.
3 Stronger Risk Management in Banking.
4 When It Makes Sense to Have Multiple Checking Accounts.